Key takeaways
- Replacement cost pays what it costs to repair or replace with new items of similar kind and quality, minus your deductible.
- Actual cash value subtracts depreciation, so older items and roofs can pay out far less.
- Replacement cost policies often pay depreciation only after you actually repair or replace the item.
- Check loss settlement separately for the dwelling, the roof and your personal property.
In this guide
- How replacement cost and actual cash value differ
- How depreciation works in a claim
- How replacement cost claims are paid
- Where each method shows up in your policy
- When actual cash value can make sense
- How to make a replacement cost claim pay in full
- Related terms to know
- The bottom line
- Frequently asked questions
Replacement cost coverage pays what it costs to repair or replace damaged property with new items of similar kind and quality, minus your deductible. Actual cash value pays replacement cost minus depreciation, so you receive what the item was worth in its used condition. Replacement cost costs more in premium but usually produces a much larger claim check.
The difference barely matters for a one-year-old television. It matters enormously for a 15-year-old roof, a houseful of aging furniture or a total loss. Here is how each method settles a claim and how to decide which your policy should use.
How replacement cost and actual cash value differ
| Feature | Replacement cost | Actual cash value |
|---|---|---|
| What it pays | Cost to repair or replace with new, similar quality | Replacement cost minus depreciation |
| Effect of age | Little or none | Older items pay much less |
| Premium | Higher | Lower |
| Payment timing | Often two stages: ACV first, depreciation after repair | Single payment |
| Best for | Primary home, roof, most belongings | Older outbuildings, budget-limited policies |
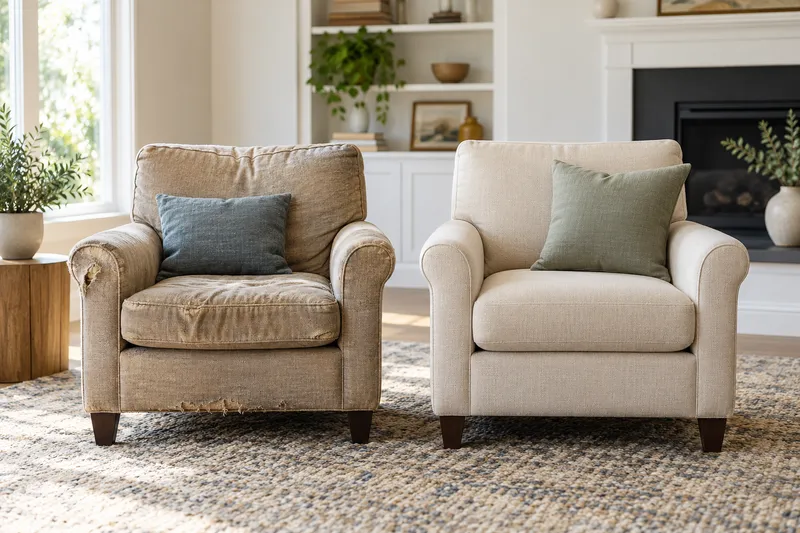
The core idea behind actual cash value is simple: the insurer pays what your property was worth the moment before the loss. A sofa that cost $2,000 eight years ago is worth much less today, even though buying a comparable new one still costs about $2,000.
How depreciation works in a claim
Depreciation reflects age, wear and expected useful life. Adjusters often estimate how long an item typically lasts, how old yours is and its condition, then reduce the replacement cost by the portion already used up. Methods differ by insurer, and some states restrict how depreciation can be applied, particularly to labor costs.
That $12,000 gap is why the loss settlement line is one of the most important terms in a policy.
How replacement cost claims are paid
Replacement cost policies commonly pay in two stages:
- Initial payment: The insurer pays the actual cash value, minus your deductible, so you can start repairs.
- Recoverable depreciation: After you complete the repair or buy the replacement and submit receipts, the insurer pays the depreciation it withheld.
Where each method shows up in your policy
A single homeowners policy can use different methods for different parts, so check each one.
The dwelling
Most standard homeowners policies cover the house itself at replacement cost, as long as you carry enough dwelling coverage. If your limit falls below a threshold, often 80% of replacement cost, the insurer may pay less or pay actual cash value instead. Our guide on how much dwelling coverage you need explains how to avoid that.
The roof
Roofs are the area where actual cash value has spread fastest. Many insurers apply actual cash value or a percentage payment schedule to roofs past a certain age, particularly in hail- and wind-prone regions. Your house might be on replacement cost while your roof is not. See how roof age affects home insurance for how insurers treat older roofs, and roofing materials compared if you are weighing a replacement.
Personal property
Belongings are frequently covered at actual cash value by default, with replacement cost available as an endorsement for an added premium. Because clothing, furniture and electronics depreciate quickly, this upgrade often makes the biggest practical difference to what you collect. Our overview of what homeowners insurance covers walks through personal property limits and sub-limits.
When actual cash value can make sense
Actual cash value is not always the wrong choice. It may be reasonable when:
- The property is an older detached shed or outbuilding you would not fully rebuild
- You are insuring a rental or vacant property on a tight budget
- Replacement cost coverage is not offered for an older roof and replacing the roof is not yet practical
- You have substantial savings and would rather self-insure part of the depreciation risk
Even then, understand how large the gap could be before accepting it. Run the math on your roof and your most expensive belongings.
How to make a replacement cost claim pay in full
Even with replacement cost coverage, how you handle the claim affects what you collect:
- Keep an inventory. A home inventory with photos, receipts and approximate purchase dates makes it easier to establish what you owned and what it costs to replace.
- Ask for the depreciation breakdown. Request a written estimate showing replacement cost, depreciation withheld and actual cash value paid for each item or line.
- Replace within the deadline. Track the time limit for completing repairs or purchases and submit receipts promptly.
- Replace with similar quality. Replacement cost generally pays for comparable items. Upgrading is usually allowed, but you pay the difference.
- Question depreciation that looks high. If an item was in excellent condition or recently repaired, provide evidence and ask the adjuster to reconsider.
These steps apply whether the loss is a single stolen laptop or a houseful of fire-damaged belongings. Our guide to filing a home insurance claim covers the broader process.
Related terms to know
- Extended replacement cost: Pays a percentage above your dwelling limit if rebuilding costs spike.
- Guaranteed replacement cost: Pays the full cost to rebuild regardless of the limit, where offered.
- Functional replacement cost: Pays to rebuild with modern, functionally equivalent materials rather than matching older ones, sometimes used for historic homes.
- Market value: What a buyer would pay for the home, including land. It is not a loss settlement method for a standard homeowners policy.
The bottom line
Replacement cost pays to put things back as they were; actual cash value pays what they were worth used. For your house, roof and belongings, replacement cost is usually worth the extra premium because depreciation can erase a large share of a claim. Check each part of your policy separately, and know the deadline for recovering withheld depreciation.
Frequently asked questions
Is replacement cost or actual cash value better?
Replacement cost is better for most homeowners because it pays enough to actually repair or replace what was damaged. Actual cash value costs less but can leave a large gap after a claim, especially for older roofs, furniture and electronics. Actual cash value can make sense for an older secondary structure or when replacement cost is unavailable or unaffordable.
How is depreciation calculated on an insurance claim?
Adjusters typically estimate an item's useful life and current age or condition, then reduce its replacement cost accordingly. A roof with a 25-year expected life that is 15 years old might be depreciated by around 60%. Methods vary by insurer and state, and some states limit depreciating labor costs, so ask for the depreciation breakdown in writing.
What is recoverable depreciation?
On a replacement cost policy, the insurer often pays the actual cash value first, then pays the withheld depreciation once you complete the repair or replacement. That withheld amount is called recoverable depreciation. Policies usually set a deadline for completing the work and submitting receipts, so check the time limit before you delay repairs.
Why does my policy pay actual cash value on my roof?
Many insurers now apply actual cash value or a roof payment schedule to older roofs, even when the rest of the house is covered at replacement cost. It is a way to limit claim costs in hail and wind-prone areas. You can sometimes restore replacement cost roof coverage by replacing the roof or choosing a different insurer.
How much more does replacement cost coverage cost?
Replacement cost coverage for personal property typically adds a modest percentage to the premium compared with actual cash value, though the exact difference varies by insurer and region. Given how much depreciation can reduce a payout on older belongings, many homeowners find the extra premium worthwhile. Ask for quotes both ways to see the real difference.
Official Resources & Further Reading
Use these resources to check current guidance. Requirements and availability may vary by state and provider.
This guide is for general educational purposes and is not individualized financial, legal, tax or insurance advice. Product terms, rates and availability vary by provider and location. How we make money.