Key takeaways
- Make sure everyone is safe, then take reasonable steps to prevent further damage and keep receipts for emergency repairs.
- Document everything with photos and video before cleanup, and keep damaged items until the adjuster has seen them.
- Report the claim promptly and keep a written log of every call, email and person you speak with.
- You can question a low offer by providing contractor estimates, invoking appraisal or contacting your state insurance department.
In this guide
- Before you file: should you make a claim?
- Step 1: Stay safe and prevent further damage
- Step 2: Document the damage thoroughly
- Step 3: Report the claim to your insurer
- Step 4: Work with the adjuster
- Step 5: Submit proof of loss and review the settlement
- What to do if you disagree with the offer
- The bottom line
- Frequently asked questions
To file a home insurance claim, first make sure everyone is safe and prevent further damage. Then photograph and document the damage, contact your insurer or agent to report the loss, meet with the adjuster, submit your proof of loss and repair estimates, and review the settlement before accepting it. Keep records of everything.
The process sounds simple, but small mistakes, like throwing away damaged items or waiting weeks to report, can shrink your payout. Here is what to do at each stage, plus how to push back if the offer seems low.
Before you file: should you make a claim?
Not every loss is worth a claim. Check two things first:
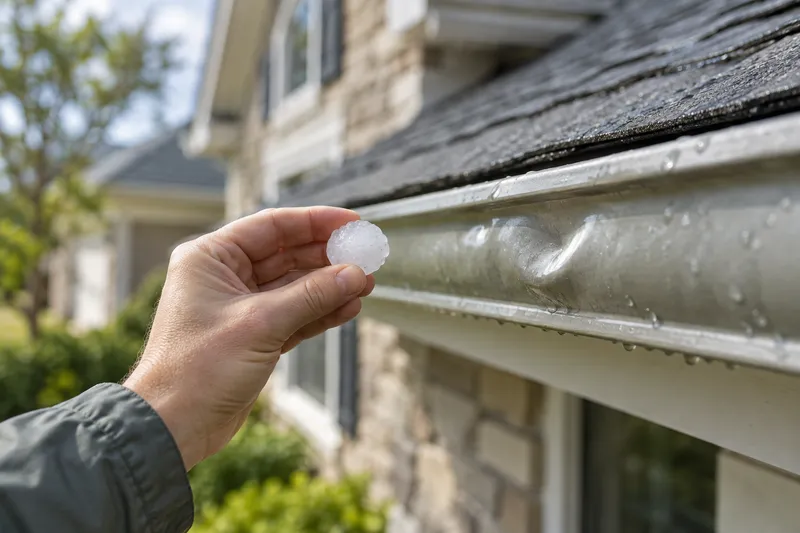
- Is it covered? Most policies cover sudden, accidental damage such as fire, wind, hail, theft and burst pipes. Flooding, earthquakes, wear and tear, and gradual leaks are typically excluded. Our guide to what homeowners insurance covers explains the usual lines.
- Is it well above your deductible? If the damage costs only a little more than your deductible, the payout will be small and the claim may still affect your future premiums.
That said, if there is any chance the damage is larger than it looks, such as hidden water damage, report it. Reporting is not the same as receiving a payout, but ask your insurer how it records inquiries if you are concerned. For more on deductible choices, see our guide to home insurance deductibles.
Step 1: Stay safe and prevent further damage
Leave the home if it is unsafe and call emergency services if needed. Once it is safe, your policy generally requires you to take reasonable steps to protect the property from more damage. Examples include:
- Shutting off the water main after a burst pipe
- Covering a damaged roof with a tarp
- Boarding up broken windows or doors
- Moving undamaged belongings away from water
Keep every receipt for supplies and emergency services. Reasonable mitigation costs are usually reimbursed as part of the claim. Hold off on permanent repairs until the insurer has had a chance to inspect, unless waiting would cause more damage.
Step 2: Document the damage thoroughly
Before you clean up, take clear photos and video of every damaged area and item. Capture wide shots of each room and close-ups of the damage. Then:
- Make a list of damaged or destroyed belongings with approximate age, purchase price and brand or model where possible.
- Gather receipts, bank or card statements, and old photos that show your belongings.
- Keep damaged items until the adjuster has seen them or told you they can go. If you must discard something for health reasons, such as soaked carpet, photograph it first and keep a sample.
- For theft or vandalism, file a police report and get the report number.
Step 3: Report the claim to your insurer
Contact your insurer by phone, app, website or through your agent as soon as practical. Have your policy number, the date and cause of the loss, and a brief description ready. You will usually get a claim number and be assigned an adjuster.
From this point on, keep a claim log: the date, time, name and a summary of every conversation, and follow up important calls with an email so there is a written record.
If the home is unlivable, ask about additional living expenses (sometimes called loss of use). This coverage can pay for a hotel or rental and extra costs like restaurant meals above your normal grocery bill. Keep all receipts.
Step 4: Work with the adjuster
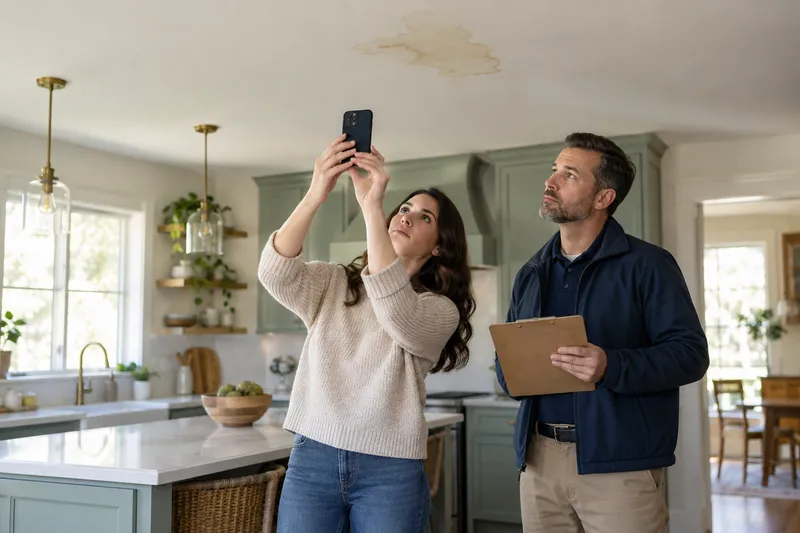
The adjuster inspects the damage, reviews your documentation and estimates the cost of repairs. To get the most from this visit:
- Be present, walk the adjuster through all damage and point out anything that is easy to miss.
- Share your photos, inventory and any contractor estimates you already have.
- Ask how long the process usually takes and what else they need from you.
- Ask for a copy of the adjuster's estimate in writing.
It helps to get at least one independent estimate from a licensed contractor. If it is higher than the adjuster's, share it and ask the adjuster to explain the differences line by line.
Step 5: Submit proof of loss and review the settlement
Many insurers require a signed proof of loss, a sworn statement of what was damaged and what you are claiming, often within a deadline stated in your policy. Fill it out carefully and keep a copy.
When the offer arrives, understand how it was calculated:
| Settlement term | What it means for you |
|---|---|
| Deductible | Subtracted from the covered loss amount |
| Actual cash value (ACV) | Replacement cost minus depreciation for age and wear |
| Replacement cost value (RCV) | Cost to repair or replace with similar new materials |
| Recoverable depreciation | The amount withheld under an RCV policy until repairs are completed |
| Mortgagee on the check | Your lender may be a co-payee on structural payments |
Many replacement cost policies first pay the ACV, then release the withheld depreciation after you complete repairs and send invoices. Our guide to replacement cost vs. actual cash value explains why the first check is often lower than expected. Roofs can be an exception: some policies settle roof damage at ACV only, which we cover in our guide to roof age and home insurance.
What to do if you disagree with the offer
If the settlement seems too low or a claim is denied:
- Ask for a written explanation that cites the specific policy language.
- Provide more evidence, such as detailed contractor estimates, engineer reports or additional photos.
- Invoke appraisal if your policy has an appraisal clause and the dispute is about the dollar amount. Each side picks an appraiser, and an umpire resolves differences.
- Contact your state insurance department. Regulators accept consumer complaints and can look into how a claim was handled.
- Consider professional help for large or complex claims. A licensed public adjuster works for you, usually for a percentage of the settlement, and an attorney may be appropriate if you believe the claim was handled in bad faith.
The bottom line
A smooth claim starts before the adjuster arrives: protect the property, document everything, report promptly and keep a written trail. Understand how your settlement is calculated, especially depreciation and deductibles, and do not hesitate to ask questions or push back with evidence if the numbers do not match what it will actually cost to repair your home.
Frequently asked questions
How long do I have to file a home insurance claim?
Policies usually require you to report a loss promptly or as soon as practical, and many set deadlines for submitting a signed proof of loss or filing a lawsuit, sometimes one to two years after the loss. State laws also affect these deadlines. Report damage as soon as you can, since delays can make it harder to prove what happened and may give the insurer grounds to limit payment.
Should I file a claim for small damage?
Not always. If the repair cost is only slightly above your deductible, a claim may pay little while still going on your claims history, which can lead to a higher premium or loss of a claims-free discount. For small losses, get a repair estimate first, compare it with your deductible, and consider paying out of pocket.
Do I have to use the contractor my insurance company recommends?
Generally, no. Insurers may suggest preferred contractors, and using one can speed things up, but in most cases you can choose your own licensed contractor. Your insurer will still pay based on its assessment of a reasonable repair cost, so get a detailed written estimate and share it with the adjuster if it differs from theirs.
Why did I get two checks or a check with my mortgage lender's name on it?
If you have a mortgage, the lender is usually listed on your policy and structural damage payments are often made out to both you and the lender. The lender may hold the funds and release them as repairs progress. With replacement cost policies, you may also first receive the depreciated value and then a second payment once repairs are completed.
What can I do if my home insurance claim is denied?
Ask for the denial in writing with the specific policy language it relies on. Review your policy, gather more evidence such as contractor reports or photos, and submit a written appeal. You can also file a complaint with your state insurance department, use the appraisal clause for disputes about amount, or consult a licensed public adjuster or attorney for large claims.
Official Resources & Further Reading
Use these resources to check current guidance. Requirements and availability may vary by state and provider.
This guide is for general educational purposes and is not individualized financial, legal, tax or insurance advice. Product terms, rates and availability vary by provider and location. How we make money.