Key takeaways
- Homeowners insurance does not cover flood damage, so you need a separate flood policy from the NFIP or a private insurer.
- NFIP policies generally take effect 30 days after purchase, with limited exceptions such as buying at a mortgage closing.
- NFIP residential limits are $250,000 for the building and $100,000 for contents; private policies may offer more.
- Homes outside high-risk flood zones still flood, and coverage there is often less expensive.
In this guide
Flood insurance is a separate policy that pays for flood damage to your home and belongings, which standard homeowners insurance excludes. You can buy it through the federal National Flood Insurance Program (NFIP) or from private insurers. NFIP policies usually take 30 days to take effect, so coverage must be purchased well before a storm arrives.
Flood is one of the most common and costly types of property damage, and it is also one of the most commonly uninsured. The sections below explain what a flood policy covers, how federal and private options differ and how to decide how much coverage you need.
Why homeowners insurance does not cover flood
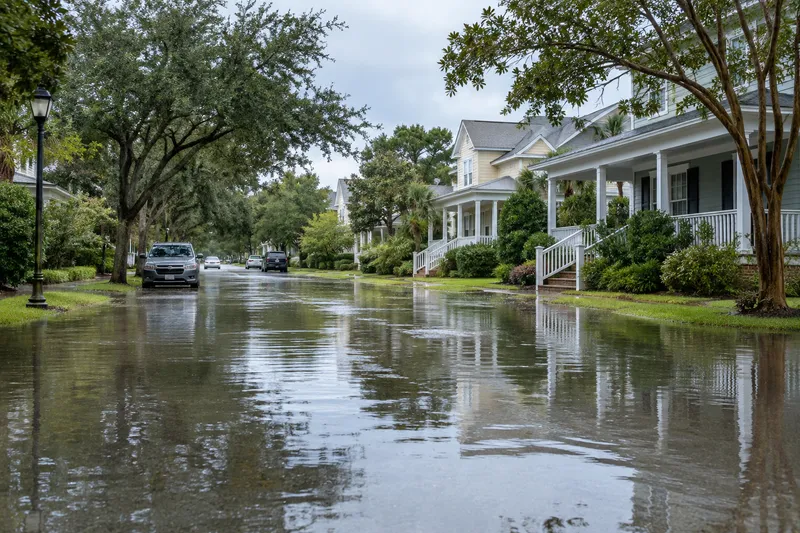
Standard homeowners policies exclude damage from surface water, overflowing rivers and lakes, storm surge, mudflow and rising groundwater. The insurance industry treats flood as a separate catastrophe risk because a single event can damage thousands of homes at once. That gap is why the NFIP was created and why private flood markets exist. For a full rundown of what a standard policy includes and excludes, see what homeowners insurance covers.
What flood insurance covers
An NFIP policy has two separate parts, and you choose limits for each.
- Building property: The structure and its foundation, electrical and plumbing systems, furnaces and water heaters, built-in appliances, permanently installed carpeting and cabinets, and detached garages within certain limits.
- Personal property (contents): Clothing, furniture, electronics, portable appliances such as washers and dryers, and some valuables up to sub-limits.
Contents coverage is sold separately, so a building-only policy leaves your belongings unprotected. Renters can buy contents-only coverage.
What it generally does not cover
- Additional living expenses while you are displaced (NFIP policies do not include this)
- Most finished basement items and personal property stored below ground level
- Land, landscaping, swimming pools, decks and fences in many cases
- Cars, which are covered by comprehensive auto insurance instead
- Damage from moisture or mold that you could have prevented
NFIP vs private flood insurance
| Feature | NFIP | Private flood |
|---|---|---|
| Who backs it | Federal program, sold through participating insurers and agents | Private insurers and specialty carriers |
| Building limit (residential) | Up to $250,000 | Can be higher, varies by insurer |
| Contents limit | Up to $100,000 | Can be higher, varies by insurer |
| Waiting period | Generally 30 days, with limited exceptions | Set by insurer, sometimes shorter |
| Additional living expenses | Not included | Often available |
| Basement coverage | Limited | Sometimes broader |
| Availability | Any home in a participating community | Depends on insurer appetite and location |
| Pricing | Based on property-specific risk under FEMA's current rating method | Insurer's own models; can be lower or higher |
The NFIP offers stability: it will generally write a policy in any participating community, and annual increases on existing primary-residence policies are subject to statutory caps. Private policies can offer higher limits and extras such as living expenses, but insurers can decline to renew or reprice more freely, and availability varies. Some homeowners with expensive homes carry an NFIP policy plus a private excess flood policy for the amount above federal limits.
The NFIP operates under authority that Congress must periodically reauthorize. Lapses in authorization have at times paused new policy sales, so check the current status with an agent or FEMA if you are buying during a reauthorization deadline.
The flood insurance waiting period
Most new NFIP policies take effect 30 days after purchase. The rule exists so people cannot wait until a storm is forecast to buy coverage. Common exceptions include:
- A policy purchased in connection with making, increasing, extending or renewing a mortgage loan, which can take effect at closing
- Certain purchases made shortly after a flood map revision places a property into a high-risk zone
Private flood insurers set their own waiting periods. Some are shorter, but many exclude or delay coverage if a named storm is already approaching when you apply.
Do you need flood insurance outside a flood zone?
Flood maps identify Special Flood Hazard Areas, zones with at least a 1% annual chance of flooding. If your home is in one and you have a federally backed mortgage, flood insurance is required. But flood risk does not stop at the mapped line. Heavy rainfall, overwhelmed storm drains, snowmelt and new development can flood homes in moderate- and low-risk zones, and a meaningful share of NFIP claims come from outside high-risk areas.
Because expected losses are lower outside high-risk zones, premiums there are often modest compared with the potential cost of even a few inches of water. If you are buying a home, check its flood risk and history before you close; our first-time home buyer guide covers other items worth reviewing during due diligence.
How much flood coverage to buy
Aim to cover the cost to repair or rebuild the structure, up to program limits, plus enough contents coverage for belongings on the ground and first floors. Our guide on how much dwelling coverage you need explains how to estimate rebuild cost. If that exceeds NFIP limits, consider excess or private coverage.
Flood policies also carry deductibles, often separate for building and contents. Choosing a higher deductible lowers the premium, as with any policy; see home insurance deductibles for how to weigh that tradeoff. In high-risk areas, earthquake and flood are the two big exclusions to review together, and earthquake insurance explains the other one.
The bottom line
Flood insurance fills one of the largest gaps in a standard homeowners policy. Compare NFIP and private options on limits, living expense coverage and stability, not just price, and buy well ahead of storm season because of the waiting period. Even outside mapped flood zones, the coverage is often inexpensive relative to the damage it prevents.
Frequently asked questions
Is flood insurance required?
Flood insurance is required if you have a mortgage from a federally regulated or federally insured lender and the home is in a FEMA Special Flood Hazard Area. Lenders can also require it elsewhere. Outside those situations it is optional, but because standard homeowners policies exclude flood, going without it means paying for flood damage yourself or relying on limited disaster assistance.
How long does it take for flood insurance to start?
NFIP policies generally have a 30-day waiting period before coverage begins. Exceptions include policies bought in connection with making, increasing or renewing a mortgage, which can start at closing, and certain cases tied to flood map revisions. Private flood policies set their own waiting periods, which are sometimes shorter. Buy well before storm season rather than when a storm is forecast.
Does flood insurance cover basements?
Coverage in basements is limited under NFIP policies. Building coverage generally includes essential equipment such as furnaces, water heaters, electrical panels and some fixtures, plus cleanup. Finished walls, flooring, furniture and most personal belongings stored in a basement are generally not covered. Some private flood policies offer broader basement coverage, so compare the policy language.
Can I buy flood insurance if I am not in a flood zone?
Yes. Anyone in a community that participates in the NFIP can buy an NFIP policy, and private insurers sell flood coverage in many areas as well. Premiums outside high-risk zones are often lower because expected losses are lower, yet those homes still experience flooding from heavy rain, poor drainage and overwhelmed storm systems.
Does FEMA disaster assistance replace flood insurance?
No. Federal disaster assistance is available only when a disaster is declared, and grants are generally limited and intended to make a home safe and habitable rather than fully restore it. Some assistance comes as loans that must be repaid. A flood insurance policy pays covered losses whether or not a federal disaster declaration occurs.
Official Resources & Further Reading
Use these resources to check current guidance. Requirements and availability may vary by state and provider.
This guide is for general educational purposes and is not individualized financial, legal, tax or insurance advice. Product terms, rates and availability vary by provider and location. How we make money.