Key takeaways
- Report the accident to your insurer promptly, even if you think the other driver was at fault.
- At-fault accidents commonly raise premiums, and surcharges often last three to five years.
- Not-at-fault accidents usually have little or no rate impact, though rules vary by state and insurer.
- Shopping for new quotes after a rate increase can help, since insurers weigh accidents differently.
In this guide
- What to do right after a car accident
- How to file a car insurance claim
- Dealing with the insurance adjuster
- How fault affects your rates
- How long an accident affects your insurance
- Should you pay for a small accident yourself?
- How to lower your insurance after an accident
- The bottom line
- Frequently asked questions
After an accident, you should report it to your insurer promptly, cooperate with the claim and expect a fault decision. If you are found at fault, your premium will often rise at renewal and the surcharge commonly lasts three to five years. A not-at-fault accident usually has little or no effect on your rate.
How much you pay depends on your insurer, your state, the severity of the claim and your driving history. Here is how the process works and how to limit the financial damage.
What to do right after a car accident
Your first priorities are safety and documentation:
- Check for injuries and call 911 if anyone is hurt or the scene is dangerous.
- Move to safety if the vehicles can be moved and it is legal to do so.
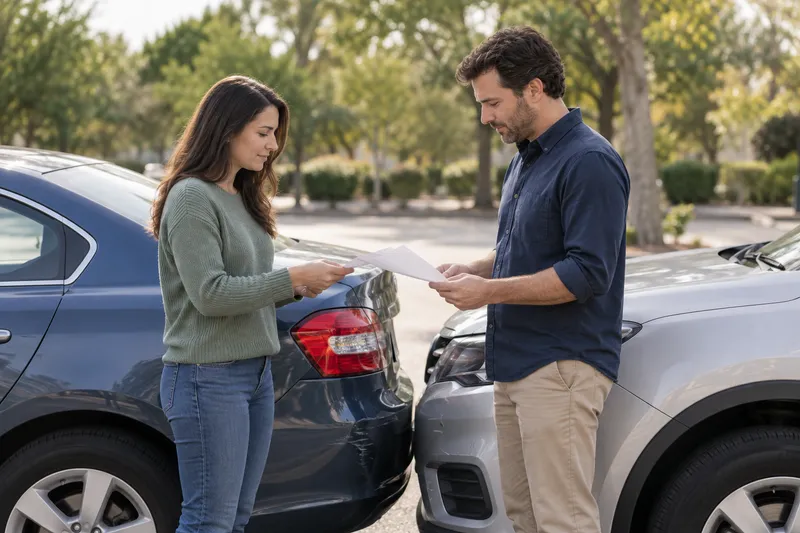
- Exchange information with the other driver: name, phone, insurer, policy number, license and plate numbers.
- Document the scene. Take photos of all vehicles, damage, road conditions, signs and license plates.
- Get a police report or report number when police respond, and note witness contact details.
- Avoid admitting fault at the scene. Stick to facts; fault is determined later.
Many states require you to report accidents above a certain damage threshold or involving injuries to police or the motor vehicle agency. Check your state's rules.
How to file a car insurance claim
Contact your insurer as soon as practical, by app, website or phone. You will usually need:
- Date, time and location of the accident
- Other driver's information and insurer
- Photos and the police report number
- A description of what happened
You can file with your own insurer or directly with the at-fault driver's insurer (a third-party claim). Filing through your own collision coverage is often faster, and your insurer may later recover costs, including your deductible, from the other company through a process called subrogation.
If the at-fault driver has no insurance or too little, your uninsured motorist coverage may pay for your injuries and, in some states, your car's damage.
Dealing with the insurance adjuster
After you file, an adjuster will review the claim, inspect the damage (in person or through photos) and decide how much the insurer will pay. A few habits help the process go smoothly:
- Respond promptly to requests for documents, photos or statements.
- Get repair estimates if the insurer allows it, and ask whether you can choose your own repair shop.
- Ask how the car will be valued if it may be a total loss. Payouts are based on actual cash value, so gather listings for comparable vehicles in case you disagree with the offer.
- Be careful with recorded statements to the other driver's insurer. You can keep answers factual and brief, and you may want legal advice if injuries are involved.
- Keep copies of everything in writing.
If you believe a claim is being handled unfairly or delayed without explanation, you can ask for a supervisor, request the decision in writing and, if needed, file a complaint with your state insurance department.
How fault affects your rates
Insurers determine fault using police reports, statements, photos and state negligence rules. In some states, fault can be shared by percentage.
| Situation | Typical rate effect |
|---|---|
| You were at fault, with a paid claim | Premium often rises at renewal; surcharge commonly lasts 3 to 5 years |
| You were not at fault | Usually little or no increase; some states restrict surcharges |
| Comprehensive claim (hail, theft, animal) | Often little effect, though frequent claims can matter |
| Accident with a DUI or serious violation | Large increase likely; SR-22 filing may be required |
In no-fault states, your own personal injury protection pays your medical costs first regardless of who caused the crash, but fault still matters for property damage and rate decisions.
How long an accident affects your insurance
Many insurers apply an at-fault surcharge for three to five years, and it often shrinks each year you stay claim-free. Once the accident ages out of your insurer's look-back window, the surcharge usually drops off at the next renewal.
Some policies include accident forgiveness, which prevents your first at-fault accident from raising your rate. It may be included for long-term customers or sold as an add-on, and a few states restrict or regulate it. Check your policy before assuming you have it.
Should you pay for a small accident yourself?
For minor damage, paying out of pocket can sometimes be cheaper than a claim that raises your premium for years. But you should still notify your insurer as your policy requires, especially if another party is involved, because injuries or damage can surface later.
How to lower your insurance after an accident
- Compare quotes. Insurers weigh accidents differently, so a rate increase is a good trigger to shop. Our guide to how to lower car insurance covers more strategies.
- Take a defensive driving course. Some insurers offer a discount, and in some states it can offset points.
- Raise your deductible if you can afford a larger out-of-pocket cost.
- Stay claim-free. The surcharge usually fades as time passes without new incidents.
- Ask about accident forgiveness when you shop, so a future mistake does not hit your rate as hard.
- Review your coverage. If the accident left you driving an older, lower-value car, dropping collision may make sense.
If you also need to file a home insurance claim, for example if a car damaged your house or garage, the process is similar; see our guide to filing a home insurance claim.
The bottom line
After an accident, focus on safety, document everything and report it to your insurer promptly. An at-fault claim will often raise your premium for three to five years, while a not-at-fault claim usually has little effect. When your rate rises, compare quotes; another insurer may price your record more favorably.
Frequently asked questions
How much does car insurance go up after an accident?
It depends on the insurer, your state, the severity of the claim and your prior record. An at-fault accident with an injury or large payout commonly causes a noticeable increase, sometimes substantial. A minor claim may have a smaller effect, and a first accident may be forgiven if you have accident forgiveness. Ask your insurer how the surcharge is calculated and how long it will apply.
Should I report a minor accident to my insurance?
Most policies require you to report accidents promptly, and failing to do so can jeopardize coverage if the other party later claims injury or damage. Reporting an accident is not the same as filing a claim for payment. If damage is minor and nobody was hurt, you can report it and still choose to pay small repairs yourself, but ask your insurer how they treat reported incidents.
Does a not-at-fault accident raise car insurance?
Generally, a not-at-fault accident has little or no effect on your rate, and several states restrict insurers from surcharging drivers who were not at fault. Still, some insurers consider overall claim frequency when renewing a policy. If your rate rises after an accident you did not cause, ask your insurer for an explanation and contact your state insurance department if you believe it is improper.
How long does an accident stay on your insurance record?
Many insurers look back three to five years when setting rates, so an at-fault accident often affects your premium for about that long. Claims databases used by insurers can keep records for up to about seven years, but the pricing impact typically fades before then. The exact look-back period depends on your insurer and state rules.
Can my insurance company drop me after an accident?
An insurer usually cannot cancel a policy mid-term over a single accident, since states limit mid-term cancellations to specific reasons like nonpayment or fraud. However, an insurer may choose not to renew your policy, particularly after multiple at-fault accidents or a serious violation. States typically require advance written notice of nonrenewal, which gives you time to shop for coverage.
Official Resources & Further Reading
Use these resources to check current guidance. Requirements and availability may vary by state and provider.
This guide is for general educational purposes and is not individualized financial, legal, tax or insurance advice. Product terms, rates and availability vary by provider and location. How we make money.