Key takeaways
- Roofers price in squares, and one square equals 100 square feet of roof surface, not floor space.
- Asphalt shingles are usually the least expensive; metal, tile and slate can cost several times more per square.
- Tear-off, decking repairs, pitch, complexity and local labor rates can move a quote as much as material does.
- Get several itemized written quotes and check how a new roof could affect your home insurance.
In this guide
Roof replacement cost is usually priced per square, with one square equal to 100 square feet of roof surface. Asphalt shingles commonly run somewhere around $350 to $600 per square installed, while metal, tile and slate can cost two to six times more. Size, pitch, tear-off and local labor rates shape the final price.
Those are broad ballparks, and actual prices vary by region, contractor, season and material costs at the time you buy. The goal of this guide is to help you estimate a realistic range, understand every line of a roofing quote and avoid costly surprises once the old roof comes off.
How roofers price a roof replacement
Roofers measure your roof in squares. A square is 100 square feet of roof surface, so a roof with 2,000 square feet of surface is 20 squares. Because roofs are sloped and overhang the walls, the surface area is larger than your home's floor plan.
Contractors also add a waste factor, often around 10% to 15%, for cut shingles, ridges, hips and valleys. Complex roofs with many angles need more.
Roof replacement cost by material
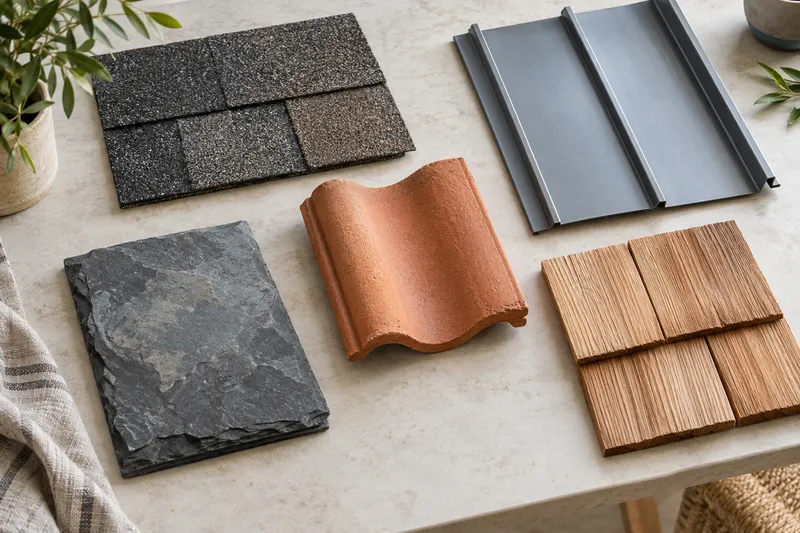
Material is the biggest single driver of price. The ranges below are rough installed ballparks per square and will vary widely by location and product.
| Material | Rough installed cost per square | Typical lifespan |
|---|---|---|
| Asphalt shingles (3-tab or architectural) | About $350 to $600 | Roughly 15 to 30 years |
| Metal (steel panels or shingles) | About $600 to $1,600, higher for standing seam or copper | Roughly 40 to 70 years |
| Wood shakes or shingles | About $600 to $1,000 | Roughly 20 to 40 years |
| Clay or concrete tile | About $650 to $1,300+ | Roughly 50 years or more |
| Synthetic (composite slate or shake) | About $700 to $1,300 | Roughly 30 to 50 years |
| Natural slate | About $1,500 to $3,000+ | Can exceed 75 years |
For a deeper comparison of durability, weight and climate fit, see our guide to roofing materials compared.
Other factors that drive the price
| Factor | How it affects cost |
|---|---|
| Roof size | More squares mean more material and labor |
| Pitch | Steep roofs need safety equipment and slow the crew |
| Complexity | Dormers, valleys, skylights and chimneys add labor and flashing |
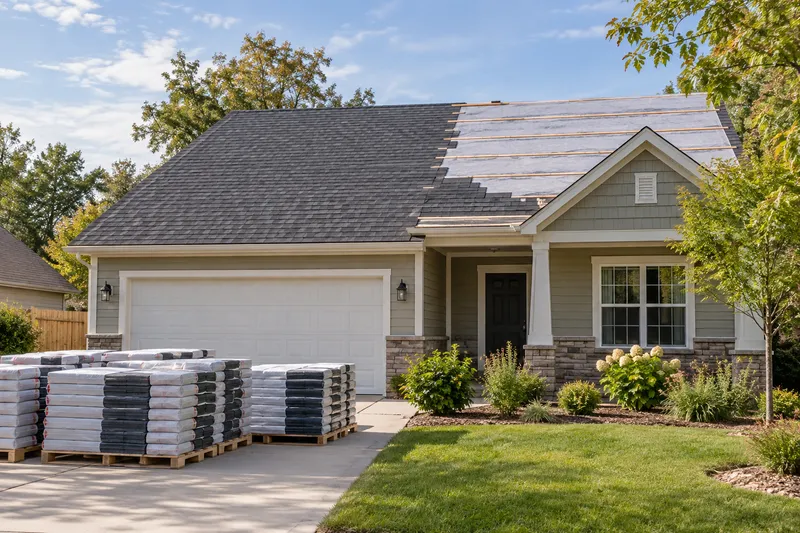
| Tear-off | Removing and disposing of old layers adds cost, more with multiple layers |
| Decking | Rotted or damaged plywood must be replaced, often priced per sheet |
| Underlayment and ventilation | Code-required ice barrier, vents and upgrades add to the total |
| Permits | Most areas require a permit and inspection |
| Location and season | Labor rates and demand, especially after storms, vary widely |
Hidden costs to plan for
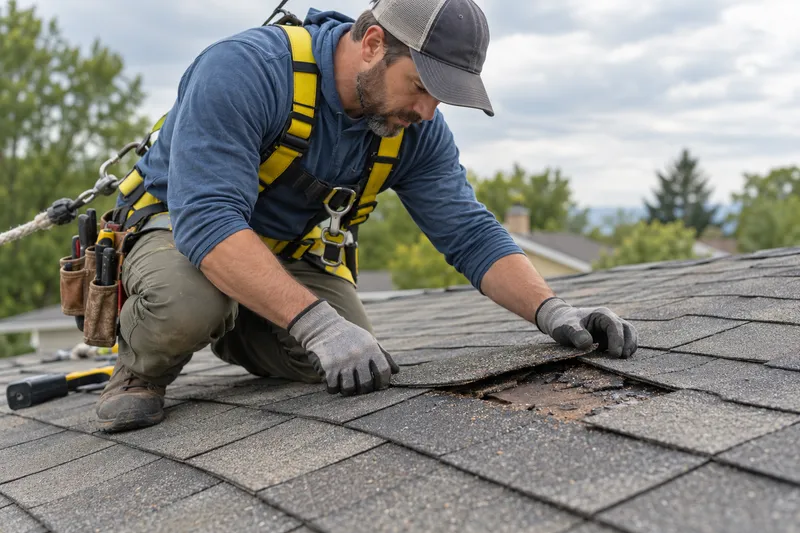
Decking damage is the most common surprise, because it is not visible until the old roof is removed. A good quote includes a per-sheet price for replacement plywood so you are not negotiating after the crew starts. Flashing, drip edge, gutters and ventilation upgrades can also add cost.
How to compare roofing quotes
Price matters, but so does what the price includes. When quotes arrive, check:
- Scope: Does it include full tear-off, new underlayment, drip edge, flashing, ridge vents and cleanup?
- Materials: Are the shingle line, underlayment and accessories named by product, not just "shingles"?
- Warranties: How long is the workmanship warranty, and does the manufacturer warranty require a certified installer?
- License and insurance: Ask for proof of liability and workers' compensation coverage, and check any state or local license.
- Payment schedule: Be cautious of large upfront deposits; many reputable contractors tie payments to milestones.
- Timeline and permits: Who pulls the permit, and when will the final inspection happen?
A quote that is far below the others may be leaving out tear-off, decking or code-required items that will show up later as change orders.
Repair or replace?
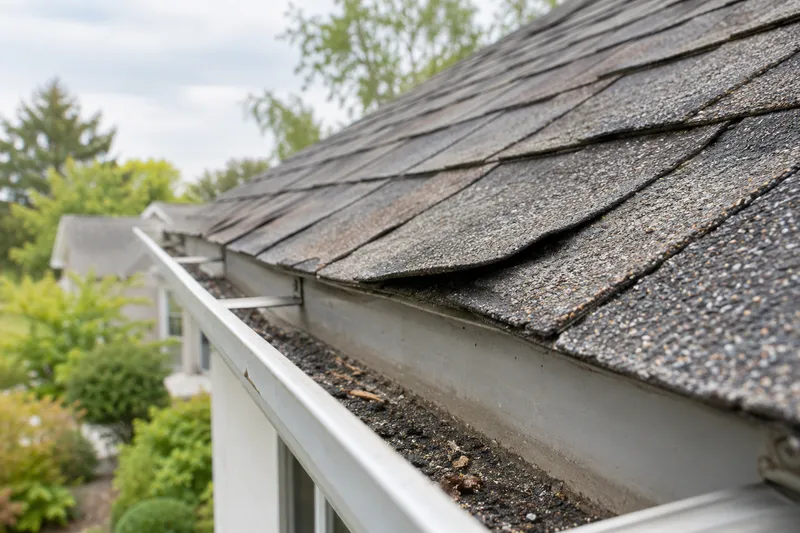
Not every leak means you need a full roof. Localized damage on a relatively young roof can often be repaired. Widespread wear, curling, granule loss or repeated leaks on an older roof point toward replacement. Our guide to roof repair vs. replacement walks through the decision, and signs you need a new roof covers what to look for.
How a new roof affects home insurance
Roof age and material matter to insurers. Many companies charge more for older roofs, limit coverage to actual cash value past a certain age, or decline to write policies on them. A new roof can improve eligibility and sometimes lower your premium, especially with impact-resistant materials in hail-prone areas. See roof age and home insurance for how this works.
If a covered storm damaged your roof, your policy may help pay for repairs or replacement minus your deductible. Wear and tear is not covered. If you are replacing a roof after a storm, our guide on how to file a home insurance claim explains documenting damage and working with the adjuster. Some policies pay older roofs only actual cash value, so the settlement may be well below the cost of a new roof.
How to pay for a new roof
Options include savings, home equity, personal loans and contractor financing. Home equity often costs less but puts your home up as collateral. Compare a cash-out refinance vs. a HELOC if you are considering equity, and read the fine print on any promotional contractor financing.
The bottom line
Roof replacement cost comes down to the number of squares, the material you choose and the complexity of your roof, with tear-off and decking adding variable costs. Use per-square ballparks only as a starting point, then compare several itemized quotes from licensed, insured contractors. Check how a new roof affects your insurance before you choose materials.
Frequently asked questions
How much does it cost to replace a roof?
For a typical asphalt shingle roof, many homeowners pay somewhere in the high four figures to the low five figures, while metal, tile and slate roofs can cost several times more. Your price depends on roof size in squares, material, pitch, complexity, tear-off, decking condition and local labor rates. Treat any average as a rough guide and get itemized quotes.
What is a roofing square?
A roofing square is 100 square feet of roof surface. Roofers use squares to measure jobs and price materials and labor. Because roofs are sloped and often overhang the walls, the roof surface is larger than the home's footprint. A steeper roof or more complex design means more squares for the same house.
Does homeowners insurance pay for a new roof?
Insurance may help pay for a roof damaged by a covered peril such as wind, hail or a falling tree, minus your deductible. It generally does not pay to replace a roof that is simply old or worn out. Some policies pay older roofs only actual cash value, which subtracts depreciation. Review your policy and roof coverage terms before a loss.
Can you put a new roof over an old one?
Some building codes allow one layer of new asphalt shingles over an existing layer, which saves tear-off costs. But a roof-over hides the decking, adds weight, can shorten the new roof's life and may affect warranties or insurance. Many roofers and codes limit it. In most cases a full tear-off is the better long-term choice.
How can I pay for a new roof?
Common options include savings, home equity through a HELOC or cash-out refinance, personal loans and contractor financing. Home equity often costs less but uses your house as collateral. Contractor financing can be convenient but may carry fees or promotional terms. Compare the total cost of each option, not just the monthly payment.
Official Resources & Further Reading
Use these resources to check current guidance. Requirements and availability may vary by state and provider.
This guide is for general educational purposes and is not individualized financial, legal, tax or insurance advice. Product terms, rates and availability vary by provider and location. How we make money.